The buyer question
Can a Lucerne financial-services mandate - cantonal-bank advisory and risk, health or accident insurance operations, or private banking - be filled in this Central-Swiss centre, and what does the public record actually prove?
What the public record shows
The verified public record for Lucerne's financial sector is anchored by the canton's economic-development record and by the anchor institutions' own disclosures. Lucerne is home to the headquarters and regional offices of long-established banks and insurance companies: Luzerner Kantonalbank, founded in 1850, is the leading bank in Canton Lucerne - a joint-stock company since 2001 whose liabilities are fully covered by a cantonal state guarantee, and one of Switzerland's ten largest banks, with a balance sheet of CHF 62.2 billion, around 1,400 staff and 23 branches; CSS, the market leader in basic health insurance, insures more than 1.6 million people with around 2,700 employees across some 100 agencies; the two Lucerne health insurers CSS and Concordia are among the largest in Switzerland; and the Swiss Accident Insurance Fund Suva has its headquarters in the city of Lucerne (records via LUKB, Lucerne Business and Wikipedia). UBS, Valiant Bank and Migros Bank as well as private banks such as Reichmuth & Co or Julius Baer are also represented at numerous locations in the canton (record via Lucerne Business).
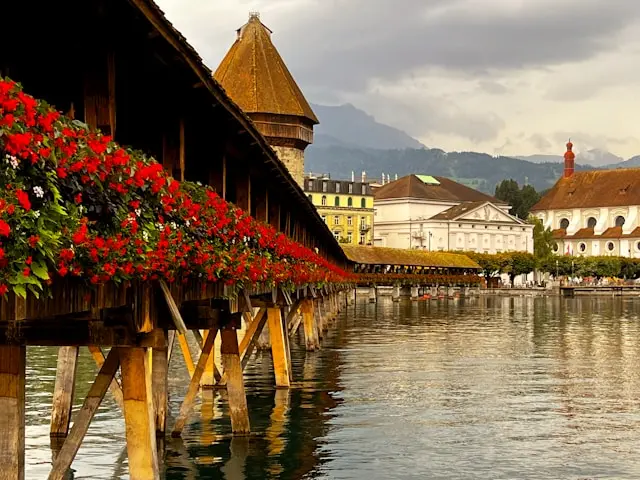
The city's standing and reach are documented too: Lucerne, with approximately 86,700 people, is the most populous city in Central Switzerland and a nexus of economics, transport, culture and media, connected to Zurich by 40 trains a day with an average journey time of 48 minutes (record via Wikipedia). That documents the market's structure and its reach toward Switzerland's largest banking centre. It does not report vacancies, pay or candidate availability for any single Lucerne institution.
The regulatory calendar is on the record: FINMA Circular 2023/1 on operational risks and resilience for banks has been in force since 1 January 2024; the Federal Council opened its consultation on amending the Banking Act and the Capital Adequacy Ordinance on 26 September 2025, running to 9 January 2026; the Swiss Climate Scores, launched in 2022, remain a voluntary disclosure framework for financial products; and LUKB's strategy announcement of 13 November 2025 commits its 2026-2030 period to investments in data- and AI-driven banking (records via FINMA, the Federal Council and LUKB). What compliance capability each institution has built against that calendar, and what it still needs to hire, is not in the public record.
What changes in this market
Lucerne mandates split by regulated function, and the evidence that proves one rarely proves another. Cantonal-bank mandates prove themselves in advisory depth and risk discipline carried under a public guarantee and a dense regional branch network. Insurance mandates prove themselves in claims, prevention and health-data operations delivered at more-than-a-million-customer scale. Private-banking mandates prove themselves in book growth and cross-border advisory. Each function proves itself against the city's anchored structure - a cantonal bank of roughly 1,400 staff and a market-leading health insurer of roughly 2,700 employees - rather than against a national average. Whether Zurich's banks price the same professionals away is real but unmeasured in any located public record; treat it as a hypothesis to test against the live mandate, not as an established differential.
KiTalent's mandate analysis
- Name the regulated function first - cantonal-bank advisory and risk, health or accident insurance operations, or private banking; they certify differently and answer to different supervisory calendars.
- Treat the anchor map as the competitive set: with LUKB, CSS, Concordia and Suva headquartering in one city, the rival bidder for a senior specialist may already be local - verify from candidate offer histories.
- Anchor compensation in the live mandate: no located public source publishes a Zurich-Lucerne salary differential or a verified technology-investment total for either anchor - a benchmark built on one would be invention.
- Ask any search partner for contacted, assessed and validated candidates per regulated function before accepting market narratives as evidence of availability.
Where the public record stops
No located primary public record verifies a combined technology-investment total for Lucerne's anchor institutions, an executive salary premium for Zurich over Lucerne, vacancy-duration or time-to-fill figures, compliance-vacancy rates, or sub-canton headcounts for Lucerne employers. LUKB's 2026-2030 strategy announces investments in data- and AI-driven banking without publishing an amount. What the public record can prove stands above, with its dates attached.
Sources
- Luzerner Kantonalbank - company record (lukb.ch)
- LUKB media release, 13 November 2025 - strategy period 2026-2030
- Lucerne Business - Financial industry and insurance
- Lucerne Business - CSS company profile
- Wikipedia - Lucerne (city record)
- FINMA - Circular 2023/1 'Operational risks and resilience - banks'
- Federal Council / FDF - consultation on the Banking Act and Capital Adequacy Ordinance, 26 September 2025
Related KiTalent research
- The Market Map Is Not the Shortlist: helps a buyer choose between testing the Lucerne financial-services market and commissioning a search with contacted, assessed and validated candidates
- How to Assess a Leader Beyond Competencies: the method for testing leadership evidence, applied here across cantonal-bank, insurance-operations and private-banking mandates